The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Seasonal repayments can help align farm machinery finance with agricultural income cycles, but the right structure depends on cash flow timing, lender criteria, equipment use and total finance cost.
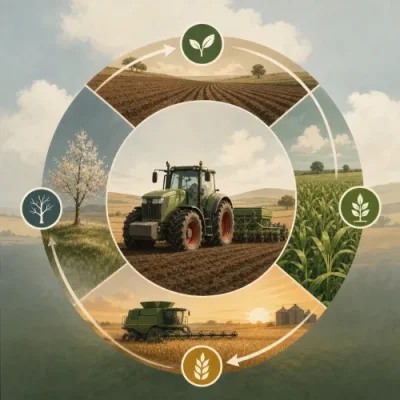
Seasonal repayments for farm machinery finance are designed to recognise that many Australian farms do not earn income evenly across the year. Instead of requiring the same repayment every month, some finance structures may allow repayments to be timed around harvest proceeds, livestock sales, contract income or other predictable cash-flow events.
This article explains how seasonal repayment options may be structured, what lenders may consider, and the risks farmers and agribusiness owners should weigh before choosing a repayment schedule. It is general information only and does not take into account your objectives, financial situation or needs.
What are seasonal repayments for farm machinery finance?
Seasonal repayments are repayment arrangements that aim to better match debt commitments with the timing of farm income. They are commonly considered where a farmer needs equipment before revenue is received, such as buying a tractor before sowing, upgrading harvest machinery before a crop comes off, or financing handling equipment before a livestock turn-off period.
Unlike a standard equal monthly repayment schedule, a seasonal structure may involve lower repayments in quieter months and larger repayments when income is expected. The exact options available depend on the lender, the finance product, the applicant’s financial position, the type and age of the machinery, and the strength of the supporting information provided.
For a broader overview of equipment funding options, you can read more about farm machinery loans and how finance may be used for agricultural equipment purchases.
Common ways seasonal farm equipment loan repayments may be structured
There is no single standard seasonal repayment model. Lenders may offer different structures depending on the asset, loan purpose and the farm’s income pattern. Common approaches include the following.
Monthly repayments with seasonal adjustments
Some borrowers may still make monthly repayments, but with amounts adjusted to reflect seasonal cash flow. For example, repayments may be lower during input-heavy months and higher after a major income period.
This can provide regularity while still recognising that a farm’s cash position may vary across the year. However, changing the repayment amount does not remove the need to meet the total repayment obligation over the term.
Quarterly, half-yearly or annual repayments
Some machinery finance arrangements may be structured with less frequent repayments, such as quarterly, six-monthly or annual payments. These may suit farms with relatively concentrated income events, provided the borrower can manage cash reserves between repayment dates.
Less frequent repayments can feel more aligned with seasonal income, but they may also require stronger budgeting discipline. A large repayment can create pressure if commodity prices, yields, sale timing or operating costs do not match expectations.
Interest-only periods or reduced repayments
In some cases, a lender may allow an initial interest-only period or a period of reduced repayments. This may be relevant where machinery is needed before it contributes to revenue, such as before a first harvest or production cycle.
These structures may improve short-term cash flow, but they can increase the amount of principal left to repay later. Depending on the contract, they may also affect the total interest paid over the life of the finance.
Balloon or residual amounts
A balloon or residual is a larger amount due at the end of the finance term. It can reduce scheduled repayments during the term, but the borrower must plan for how the final amount will be paid, refinanced or managed.
For farm machinery, the suitability of a balloon or residual may depend on the expected resale value of the equipment, hours of use, maintenance, market demand and the farm’s future replacement plans. It should not be treated as a way to avoid repayment obligations.
Repayment timing linked to specific farm events
Some farms seek repayment dates that align with known income events, such as grain sales, wool cheques, cattle sales, milk income cycles, contract harvesting income or seasonal produce payments. A lender may ask for evidence that those income events are realistic and repeatable.
Event-linked timing can be useful, but it needs to account for practical delays. Settlement of produce sales, processor payment timing, weather disruptions and supply-chain issues can all affect when cash actually lands in the business account.
Matching repayments to agricultural finance cash flow
A seasonal repayment structure usually starts with a cash-flow map. This means setting out when money is expected to come in, when major costs are due, and when machinery repayments can be met without creating unnecessary pressure on working capital.
Useful cash-flow inputs may include:
- expected sale months for crops, livestock, milk, wool, horticulture or other produce;
- major input costs such as seed, fertiliser, feed, labour, fuel, freight, irrigation, chemicals and repairs;
- existing finance commitments, lease payments and overdraft usage;
- insurance, rates, tax obligations and other recurring business expenses;
- planned maintenance, replacement parts and machinery downtime risk;
- seasonal reserves needed for dry periods, delayed harvests or price changes.
The goal is not simply to choose the lowest near-term repayment. It is to test whether the repayment pattern remains manageable across a realistic farm year, including less favourable scenarios.
When comparing potential repayment amounts, a calculator can help model different loan terms and repayment assumptions. For example, you may wish to use a finance calculator as a starting point, while remembering that actual lender offers, interest rates, fees and terms depend on individual circumstances and provider criteria.
Examples of seasonal repayment patterns
The right structure depends on the enterprise. The following examples are illustrative only and are not recommendations.
| Farm income pattern |
Possible repayment approach |
Key risk to consider |
| Broadacre cropping with one or two major sale periods |
Lower repayments through growing season and larger repayments after expected grain sales |
Yield, price and delivery timing may affect available cash |
| Livestock operation with planned turn-off periods |
Quarterly or seasonal repayments aligned with expected livestock sales |
Market prices, animal condition and transport availability may change sale proceeds |
| Dairy or other enterprise with more regular income |
Monthly repayments, potentially with adjustments around higher-cost periods |
Input cost increases may reduce surplus cash even with regular income |
| Contracting business using machinery across seasonal work |
Repayments weighted toward peak contracting income months |
Weather delays or fewer contracts may reduce expected revenue |
Farmers with crop-specific cash-flow considerations may also find the site’s article on Crop Farming: Farm Machinery Finance useful as a more targeted companion guide.
What lenders may assess before agreeing to seasonal repayments
Lenders generally want to understand whether the proposed repayment pattern is credible and affordable. While requirements vary, they may consider factors such as:
- farm trading history and seasonal income records;
- recent financial statements, tax returns or management accounts;
- bank statements and existing debt commitments;
- asset and liability position;
- the type, age, condition and value of the machinery;
- the borrower’s credit history;
- how the equipment will support farm operations or income;
- the requested term, deposit, balloon amount or residual value;
- exposure to seasonal, climate, commodity price or market risks.
A lender may be more comfortable with seasonal repayments where the borrower can clearly show when income is expected and how repayments will be funded if the season is weaker than planned.
Interest, fees and total cost implications
Seasonal repayments can assist with timing, but they do not necessarily reduce the total cost of finance. In some structures, paying less principal early in the loan may mean interest is calculated on a higher outstanding balance for longer.
Before choosing a seasonal structure, consider asking:
- How is interest calculated during lower-repayment periods?
- Will the total interest cost be higher than with equal monthly repayments?
- Are there account-keeping, establishment, early payout or variation fees?
- What happens if a large seasonal repayment is missed or delayed?
- Can repayment dates be changed if sale proceeds arrive later than expected?
- Is a balloon or residual amount required, and how realistic is the planned exit strategy?
The repayment schedule should be assessed alongside total finance cost, not in isolation. A repayment that feels comfortable in the short term may still be expensive or unsuitable if it creates a larger burden later.
Benefits of seasonal farm income loans
Where appropriate and available, seasonal repayment options may help farmers and agribusiness owners:
- align repayments more closely with revenue cycles;
- preserve working capital during planting, feeding or production periods;
- acquire machinery before it is needed for a key operating window;
- reduce pressure during months with high input costs;
- plan debt commitments around predictable income events.
These potential benefits depend on the borrower’s circumstances, the finance structure, and the lender’s approval criteria. Seasonal repayments are not automatically suitable for every farm business.
Risks and limitations to understand
Seasonal repayments can create flexibility, but they also introduce timing risk. A repayment plan built around expected income can become difficult if the income is delayed, reduced or absorbed by other costs.
Common risks include:
- Weather and production risk: drought, flood, frost, pests or disease may reduce output.
- Commodity price risk: sale prices may be lower than expected when income is received.
- Payment timing risk: settlement may occur after the scheduled repayment date.
- Cost escalation: fuel, feed, fertiliser, labour or repairs may reduce available cash.
- Over-reliance on a single income event: one delayed or poor season can affect repayment capacity.
- End-of-term pressure: balloon or residual amounts require careful planning.
It may be prudent to model a conservative scenario, not just the expected season. This can help show whether the farm could still meet obligations if income is lower or later than planned.
Questions to ask before choosing machinery finance repayment options
Before applying for machinery finance with a seasonal repayment structure, consider discussing the following questions with your accountant, adviser, broker or lender:
- Does the repayment schedule match when income is actually received, not just when production occurs?
- What cash buffer is needed before each large repayment date?
- How would a weaker season affect the ability to repay?
- Will the equipment generate or protect enough operational value to justify the finance commitment?
- What is the total cost compared with a standard repayment schedule?
- Are there penalties or fees for changing repayment timing?
- Is the loan secured against the machinery or other assets?
- What happens if the equipment needs to be sold or upgraded before the term ends?
Because lender policies and finance structures vary, it can be useful to compare options through appropriately licensed or authorised finance professionals. The site’s brokers page may help you understand how broker support can fit into the process, noting that approval, pricing and available terms depend on individual circumstances and provider criteria.
Preparing for an application
A well-prepared application may make it easier for a lender to understand the proposed repayment structure. Farmers seeking seasonal repayments may benefit from preparing:
- a clear description of the machinery and how it will be used;
- quotes, invoices or equipment details;
- recent financial statements or tax information where available;
- cash-flow forecasts showing income and expense timing;
- records of past seasonal sales or production cycles;
- details of existing loans, leases and overdrafts;
- a plan for managing weaker seasons or delayed income.
The more clearly the application connects the machinery, farm operations and repayment capacity, the easier it may be for a lender to assess whether the requested structure is appropriate under its criteria.
When seasonal repayments may not be suitable
Seasonal repayments may not be the right fit where income is highly uncertain, where the farm has limited cash reserves, or where a large end-of-season repayment would create excessive pressure. They may also be less suitable if the machinery does not have a clear operational purpose or if the proposed term extends beyond the equipment’s useful working life.
In some cases, a simpler monthly repayment structure may be easier to manage, even if it does not align perfectly with seasonal income. The right choice depends on the farm’s cash flow, risk tolerance, equipment needs and financial position.
In Conclusion
Seasonal repayments for farm machinery finance can be structured in several ways, including adjusted monthly repayments, quarterly or annual repayments, interest-only periods, and balloon or residual arrangements. The main aim is to align finance commitments with agricultural income cycles while still meeting the lender’s requirements and managing total finance cost.
Before choosing a seasonal repayment structure, consider the timing and reliability of income, the effect on interest costs, the consequences of delayed revenue, and whether the farm has enough buffer to manage a weaker season. A repayment schedule should support the business’s operating cycle rather than add avoidable cash-flow stress.
Published: Thursday, 22nd Oct 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.